
How to Read a Tenant Credit Report: A Landlord’s Guide
Read beyond the score before you approve or deny an applicant.
A tenant credit report has five parts a landlord needs to read in order: identifying information, the credit summary, ResidentScore, the payment-history section, and the detailed tradelines. The most useful piece is the 24-month payment grid because recent behavior helps show near-term rent-payment risk.
Updated May 2026: Built around the five report sections landlords need to read and the decision documentation that supports consistent screening.
Overview
This guide walks landlords through each section of a tenant credit report, shows the red and green flags to look for, explains what a credit report cannot tell you, and gives a practical process for turning the report into a consistent rental decision.
TL;DR: Read identity, credit summary, ResidentScore, payment history, and tradelines in order. Then document the decision with specific reasons and apply the same criteria to every applicant.
Sample Credit Report
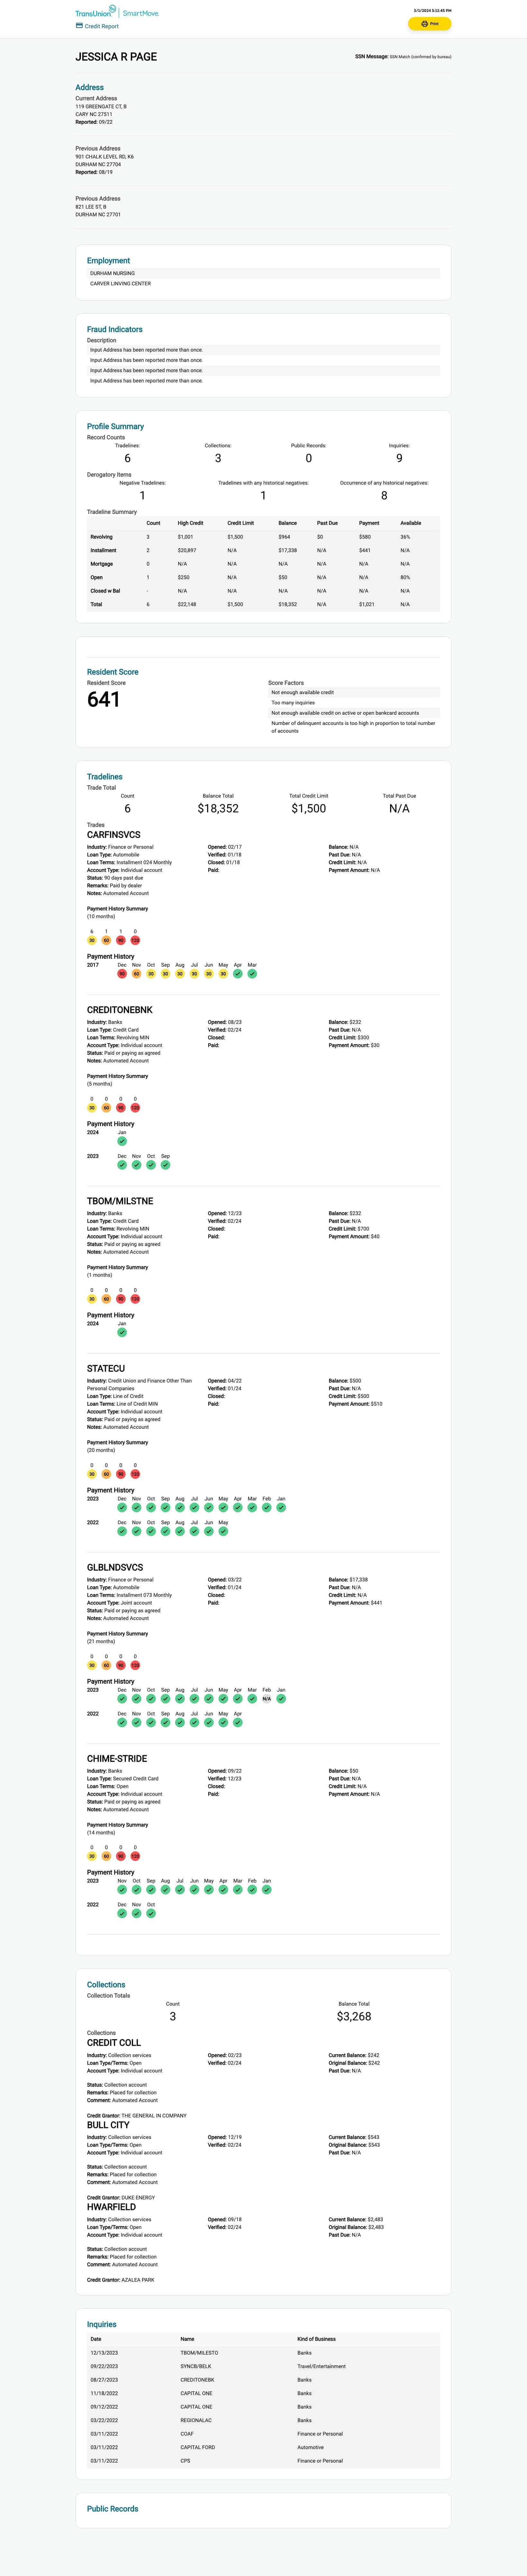
Use the sample tenant credit report to see how bureau information is organized for rental screening. The full report is long, so this preview is contained in a scrollable card to keep the page clean.
- ResidentScore: a rental-specific score used as an entry point, not the whole decision.
- 24-month grid: the payment-history area that helps show recent consistency or active stress.
- Tradelines: individual account details, balances, limits, payment status, and history.
- Collections and public records: review dates, amounts, and whether the issue is resolved.
Why a Tenant Report Differs from a Standard Credit Check
A standard consumer credit report is built to help lenders evaluate loans. A tenant credit report reorganizes credit-bureau information to highlight what predicts rent payment: recent payment patterns, rental-related collections, and a rental-specific score.
That means the report leads with ResidentScore rather than only a general-purpose score, surfaces recent payment behavior prominently, uses a soft inquiry that does not affect the applicant’s credit, and is formatted for rental decisions.
Section 1: Identifying Information
This is the first verification checkpoint. Confirm you are reviewing the right person and that the report matches the application. Look at full legal name, date of birth, current and previous addresses, address duration, and employment information shown.
Green flags
- Consistent name and address history across the report.
- Two or more years at each address.
- Current employment details that match the application.
Red flags
- Name variations suggesting possible identity issues.
- Multiple addresses within 12 months.
- Details that do not match the rental application.
A credit report’s employment field is reported to the bureau, not independently verified. Confirm employment and income separately through income verification.
Section 2: Credit Summary
The credit summary is a quick scan of overall financial health: account mix, balances, available credit, utilization, and public records.
- Account mix: a few well-managed installment and revolving accounts can show stable management.
- Utilization: below 30% is generally more comfortable; very high utilization may signal stress.
- Public records: bankruptcies, judgments, liens, and foreclosures need context, dates, and details.
Section 3: ResidentScore
ResidentScore is a rental-specific score with a stated range of 350 to 850, where higher means lower risk. Use it as an entry point to categorize the applicant before you read the details, not as the whole decision.
Avoid rigid score cutoffs. Set a consistent written threshold, apply it the same way to everyone, and review borderline cases with the underlying payment history, income, eviction search, and references.
Section 4: Payment History and the 24-Month Grid
This is the heart of the report. Payment status codes typically show whether an account is current, 30 days late, 60 days late, 90+ days late, or in collection. The 24-month grid shows each account’s status for the past two years.
Four interpretation rules
- Recency matters: a late payment last month is more important than one four years ago.
- Pattern beats incident: one old late payment is different from repeated late payments.
- Breadth matters: simultaneous late payments across accounts suggest broader stress.
- Very recent lates signal active stress: investigate before approving.
Worked example: an applicant shows one current credit-card late, a recovered student-loan late from 18 months ago, no collections, and no evictions. The older issue may show recovery, but the current late is the live concern. Verify employment, ask for context, and check remaining income after rent before deciding.
Patterns worth naming
- Sudden change: many clean months followed by recent late payments can indicate a job loss or emergency.
- Selective payment: some accounts current while others lapse may show priority patterns.
- Slow recovery: long non-payment before collection resolution may show problems are ignored too long.
Section 5: Tradelines
Tradelines are the individual account details. Review account type, creditor, date opened, limit, balance, payment, past-due amount, status, and recent history.
- Credit cards: balances near the limit can suggest stress.
- Loans: nearly paid-off loans can be positive; brand-new loans may need context.
- Collections: age, amount, and status matter.
- Closed accounts: closed in good standing is normal; closed with a balance may need review.
What a Credit Report Does Not Show
Reading a credit report well also means knowing its limits. A credit report does not:
- Verify current income or employment.
- Include criminal history or eviction filings without a money judgment.
- Show how an applicant treated a prior rental.
- Capture all rent-payment history because many landlords do not report to the bureaus.
- Explain the reason behind negative items.
That is why credit is one screening component, not the whole screen. Pair it with eviction history, criminal screening, income verification, and landlord references.
A Five-Step Process for Using the Report
- Start with the score to categorize the applicant.
- Review the 24-month payment grid for consistency, recency, severity, and breadth.
- Analyze tradelines for utilization, closures, collections, and recent openings.
- Investigate red flags with the applicant before deciding.
- Document the decision with specific, consistent reasoning.
Decision documentation protects you two ways: it makes decisions easier to defend under Fair Housing scrutiny and it forces the discipline of judging every applicant by the same written standard.
Pull a Tenant Credit Report
SmartScreen gives landlords access to ResidentScore, full credit detail, and the 24-month payment grid through a consent-based soft pull, with criminal, eviction, and income checks available in the same workflow.
Start Screening with SmartScreen →
Frequently Asked Questions
What does a tenant credit report show?
A tenant credit report consolidates credit-bureau data formatted for rental decisions: identifying information, a credit summary, a rental-specific score such as ResidentScore, payment history including a 24-month grid, and detailed tradelines for each account.
What is the most predictive part of a credit report for rent payment?
The 24-month payment-history grid is the most useful single component. It shows consistency, recency, and severity across accounts, making recent behavior easier to evaluate.
What credit score should a landlord require?
Rather than relying on a single fixed cutoff, set a consistent written threshold and apply it identically. Read the score with the underlying report, income, eviction history, and rental references.
What does a credit report not show about a tenant?
It does not verify current income or employment, does not include all eviction or criminal information, does not show rental behavior, and often does not include rent-payment history from landlords who do not report to bureaus.
About This Guide
Prepared by the SmartScreen Advisory Team. SmartScreen is operated by ClearScreening, an FCRA-certified consumer reporting agency with tenant screening experience. Credit data is provided through TransUnion.
Related Resources
- Tenant Credit Report
- Understanding ResidentScore
- The Ultimate Guide to Tenant Screening
- Tenant Income Verification
This guide provides general educational information about reading a tenant credit report and does not constitute legal or financial advice. Landlords should obtain applicant consent before screening, apply criteria consistently, and follow FCRA adverse-action requirements when a report contributes to a denial.
Ready to review tenant credit reports online?
Start with SmartScreen to request reports, review applicant risk, and keep your screening process organized.