

What Is a Security Deposit?
Financial Protection for Landlords Against Tenant Defaults
A security deposit is an upfront payment made by tenants to landlords before moving into rental properties, serving as financial protection against property damage beyond normal wear and tear, unpaid rent during tenancy or after move-out, cleaning costs exceeding standard expectations, and lease violations, including unauthorized pets or occupants.
Typically ranging $1,000-$2,000 for average rentals (equivalent to 1-2 months’ rent depending on state caps), security deposits are held in escrow accounts or backed by surety bonds, returned to tenants within 21-30 days of move-out minus itemized deductions for damages or unpaid obligations, and regulated by state-specific laws governing maximum amounts, holding requirements, refund timelines, and allowable deductions.
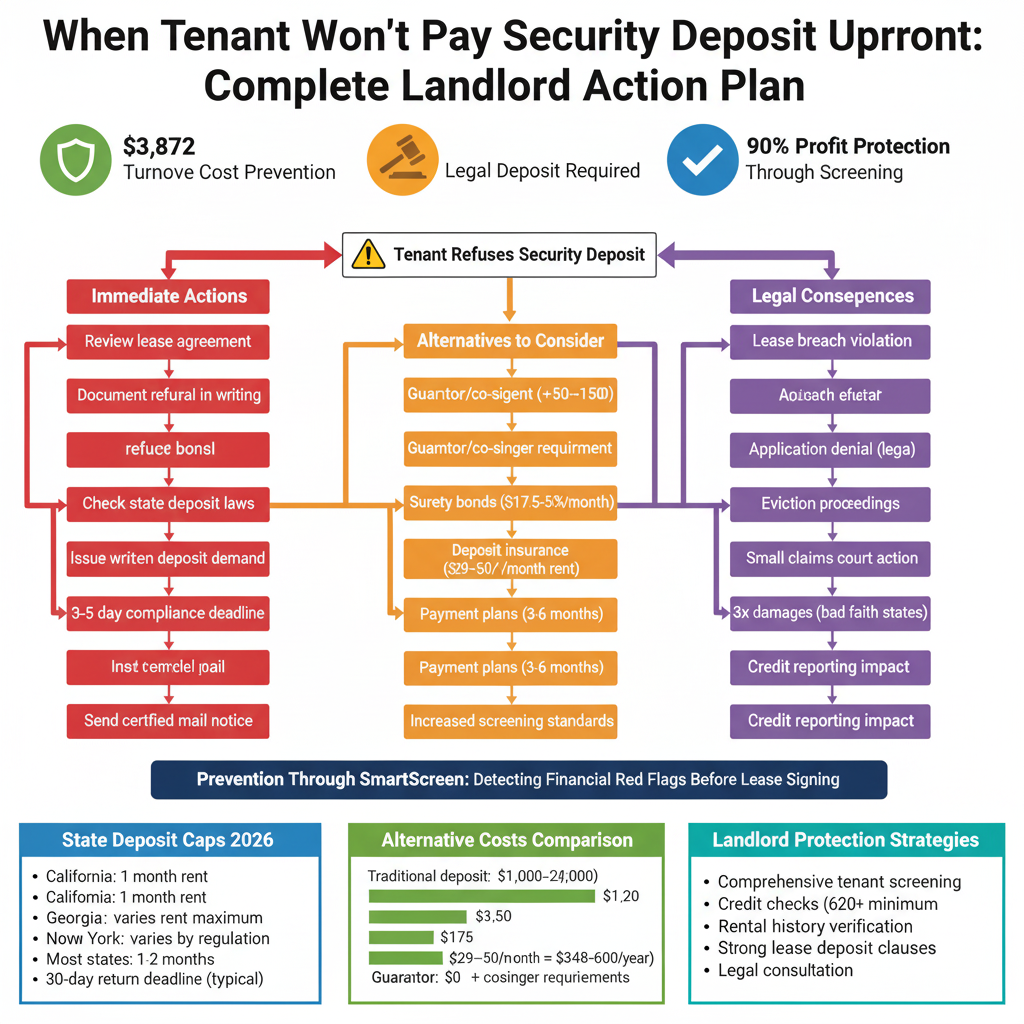
2025-2026 State Deposit Caps:
California: 1 month’s rent maximum (reduced from previous 2-3 months under AB 12, effective July 2024)
Georgia: 2 months’ rent maximum (new cap effective January 2025 under HB 404)
Florida: No statutory limit, though typically 1-2 months
New York: Varies by regulation, typically 1 month for rent-stabilized units
Most Other States: 1-2 months’ rent caps with specific regulations
Why Do Landlords Require Security Deposits Upfront?
Essential Financial Protection Against Tenant Risks
Landlords require security deposits upfront because they provide critical financial safeguards covering property damage costs averaging $500-$3,000 beyond normal wear and tear, unpaid rent averaging $1,750/month during defaults, cleaning expenses when tenants leave properties in poor condition, lease violation costs including unauthorized pet damage or occupant issues, and turnover expenses totaling $3,872 average when problematic tenants require replacement.
Without upfront deposits, landlords assume 100% of the financial risk from tenant defaults, property damage, or lease violations—whereas deposits shift partial accountability to tenants, incentivize responsible property care and rent payments, and provide landlords with immediate funds to address issues rather than pursuing costly legal collection processes.
Statistical Financial Protection:
Research shows security deposits prevent an average of $3,872 in turnover costs per incident, eliminate $1,750/month in vacancy losses during tenant replacement periods, reduce property damage expenses averaging $500-$3,000, and minimize $3,500-$10,000 in eviction costs through an upfront financial commitment, encouraging lease compliance.
Concrete Example: Deposit Value
A landlord managing a $1,500/month rental collects a $3,000 security deposit (2 months’ rent). When the tenant abandons the property mid-lease leaving $1,800 in unpaid rent, $1,200 in property damage (carpet replacement, wall repairs), and $400 in excessive cleaning costs, the $3,400 total cost is covered by the $3,000 deposit plus $400 landlord expense—preventing lengthy legal collection processes costing $3,500-$10,000 in attorney fees and court costs while enabling immediate repairs and re-rental.
Essential Financial Protection Against Tenant Risks
Landlords require security deposits upfront because they provide critical financial safeguards covering property damage costs averaging $500-$3,000 beyond normal wear and tear, unpaid rent averaging $1,750/month during defaults, cleaning expenses when tenants leave properties in poor condition, lease violation costs including unauthorized pet damage or occupant issues, and turnover expenses totaling $3,872 average when problematic tenants require replacement.
Without upfront deposits, landlords assume 100% of the financial risk from tenant defaults, property damage, or lease violations—whereas deposits shift partial accountability to tenants, incentivize responsible property care and rent payments, and provide landlords with immediate funds to address issues rather than pursuing costly legal collection processes.
Statistical Financial Protection:
Research shows security deposits prevent an average of $3,872 in turnover costs per incident, eliminate $1,750/month in vacancy losses during tenant replacement periods, reduce property damage expenses averaging $500-$3,000, and minimize $3,500-$10,000 in eviction costs through an upfront financial commitment, encouraging lease compliance.
Concrete Example: Deposit Value
A landlord managing a $1,500/month rental collects a $3,000 security deposit (2 months’ rent). When the tenant abandons the property mid-lease leaving $1,800 in unpaid rent, $1,200 in property damage (carpet replacement, wall repairs), and $400 in excessive cleaning costs, the $3,400 total cost is covered by the $3,000 deposit plus $400 landlord expense—preventing lengthy legal collection processes costing $3,500-$10,000 in attorney fees and court costs while enabling immediate repairs and re-rental.
Is It Legal for Tenants to Refuse to Pay Security Deposits Upfront?
Landlord Legal Rights to Deny Non-Compliant Applicants
No, it is not illegal for tenants to refuse security deposit payments, but landlords have full legal authority to deny rental applications from tenants unwilling to pay required deposits since deposits represent standard, lawful lease conditions in rental agreements across all 50 states—making deposit payment refusal grounds for application rejection without Fair Housing Act violations when applied consistently across all applicants.
Security deposit requirements constitute material lease terms that tenants must accept to enter rental agreements, similar to rent payment obligations, occupancy limits, or pet policies—meaning that tenants who refuse deposits breach fundamental lease conditions before tenancy even begins, justifying landlord denial of applications.
Legal Framework:
Landlords’ Rights: Legally require security deposits up to state-imposed caps as rental prerequisites
Tenant Options: Pay required deposits, negotiate alternatives (guarantors, surety bonds), or seek properties without deposit requirements
No Legal Obligation: Landlords face zero legal duty to waive or eliminate deposit requirements for applicants unable or unwilling to pay
Fair Housing Compliance:
Landlords must apply identical security deposit requirements uniformly across all applicants regardless of race, color, national origin, religion, sex, familial status, disability, or other protected classes—but consistent deposit requirements applied to all applicants constitute legitimate business practices protecting property investments, not discrimination.
What Are the Consequences When Tenants Don’t Pay Security Deposits Upfront?
Legal and Financial Ramifications for Both Parties
When tenants refuse to pay security deposits upfront, they face immediate application denials from landlords exercising legal rights to require deposits, limited rental options since 90%+ of landlords mandate deposits as standard practice, potential eviction proceedings if deposits are withheld after lease signing, legal action including small claims lawsuits for breach of contract, negative credit reporting impacting future rental applications, and difficulty establishing tenancy without financial accountability mechanisms.
Tenant Consequences:
Application Denials:
Landlords legally refuse to rent to applicants unwilling to pay deposits, eliminating rental opportunities and forcing tenants to search extensively for deposit-free properties, which typically represent less than 10% of market inventory and often charge premium rents compensating for increased risk.
Lease Breach and Eviction Risk:
If tenants sign leases agreeing to deposit payments but subsequently refuse to pay, they commit material lease breaches justifying eviction proceedings, 3-5 day pay-or-quit notices, and potential court-ordered removal with eviction records predicting 3x higher future default risk.
Legal Financial Liability:
Landlords can sue tenants for unpaid deposits plus court costs, attorney fees, and potential triple damages in jurisdictions like Georgia, where willful deposit withholding triggers 3x penalty provisions—turning $1,500 deposit disputes into $4,500+ legal judgments.
Credit and Rental History Damage:
Unpaid deposit judgments appear on credit reports, lowering credit scores, while evictions for deposit non-payment create rental history red flags that future landlords detect through comprehensive SmartScreen background checks—severely limiting future housing options.
Landlord Consequences:
Proceeding Without Deposits Exposes Landlords to:
Property Damage Risk: Average $500-$3,000 repair costs with zero financial coverage
Unpaid Rent Exposure: $1,750/month losses during defaults without deposit offsets
Turnover Cost Burdens: $3,872 average replacement expenses fully borne by landlords
Legal Collection Challenges: Pursuing tenants for damages/rent costing $3,500-$10,000 in legal fees, often exceeding actual losses
What Are Alternatives to Traditional Security Deposits?
Modern Deposit Replacement Options for 2026
In situations where tenants cannot or won’t pay traditional security deposits upfront, several alternatives provide financial protection for landlords while reducing barriers for tenants.
Alternative 1: Surety Bonds
How Surety Bonds Work:
Tenants pay non-refundable fees ranging 17.5-35% of one month’s rent ($175-$350 for $1,000/month rentals, or approximately $262-$525 for $1,500/month properties) to third-party surety companies (Rhino, TheGuarantors, Jetty, SureDeposit) that guarantee landlords up to the full traditional deposit amount (typically 1-2 months’ rent) for property damage or unpaid rent claims.
Advantages:
Lower Upfront Costs: Tenants pay $262 surety fee versus $3,000 traditional deposit (91% reduction)
Immediate Move-In: Eliminates saving periods for deposit accumulation
Landlord Coverage: Full deposit-equivalent protection ($3,000 coverage for $262 fee)
Disadvantages:
Non-Refundable Fees: Unlike traditional deposits returned after lease end, surety fees are lost expenses
Tenant Financial Liability: Tenants remain 100% liable for damages/rent; surety companies pursue reimbursement
Annual Renewals: Fees recur yearly, totaling $262-$525 per year vs. one-time refundable deposits
Alternative 2: Deposit Insurance Programs
How Deposit Insurance Works:
Tenants pay monthly fees ranging $29-$50 ($348-$600 annually) to insurance providers (LeaseLock, Obligo) that cover landlords for property damage and unpaid rent up to $5,000 standard coverage, eliminating traditional deposit requirements while providing ongoing protection.
Advantages:
Zero Upfront Payment: No deposit or bond fees at move-in
Monthly Payment Flexibility: $29-$50/month is easier to budget than $2,000-$3,000 lump sums
Landlord Coverage: $5,000 protection exceeding typical deposit amounts
Disadvantages:
Higher Long-Term Costs: $348-$600/year surpasses surety bond fees; $1,044-$1,800 over 3 years exceeds traditional $2,000 deposits
Non-Refundable Payments: All fees are non-refundable versus deposit refunds
Tenant Financial Liability: Full responsibility for damages with provider collection efforts
Alternative 3: Guarantors or Co-Signers
How Guarantors Work:
Tenants provide financially qualified guarantors (typically parents, relatives, or close friends) who sign lease agreements guaranteeing rent payments and damage costs if tenants default—substituting personal financial backing for cash deposits.
Advantages:
Zero Cost to Tenants: No deposits, fees, or monthly payments required
Landlord Financial Security: Guarantors provide payment assurance through personal liability
Credit Building: Tenants establish rental histories without upfront capital
Disadvantages:
Guarantor Requirements: Not all tenants have qualified guarantors with sufficient income/credit
Relationship Strain: Financial dependencies on family/friends create potential conflicts
Limited Landlord Acceptance: Many landlords prefer cash deposits over personal guarantees
Alternative 4: Higher Monthly Rent
How Rent Increases Work:
Landlords waive security deposit requirements in exchange for higher monthly rent (typically a $50-$150 increase or a 3-10% premium), compensating for the increased financial risk from deposit elimination.
Advantages:
Zero Upfront Costs: Eliminates saving periods for deposit accumulation
Immediate Occupancy: Tenants move in without capital barriers
Landlord Revenue: Higher rents offset potential damage/default costs over time
Disadvantages:
Higher Long-Term Costs: $50-$150/month increases cost $600-$1,800 annually and $1,800-$5,400 over 3-year leases—exceeding typical $2,000 deposits
Unrecoverable Expenses: Unlike refundable deposits, rent premiums are permanent costs
Qualification Challenges: Higher rents may disqualify tenants from income requirements (2.5-3x ratios)
Alternative 5: Deposit Payment Plans
How Payment Plans Work:
Landlords allow tenants to spread security deposits over 3-6 months rather than paying lump sums upfront—for example, $1,500 deposits paid as $500 at move-in plus $250/month for 4 months.
Advantages:
Reduced Upfront Barriers: $500 initial payment versus $1,500 full deposit
Eventual Full Coverage: Landlords receive complete deposits within 3-6 months
Tenant Accessibility: More applicants can afford partial payments
Disadvantages:
Delayed Full Protection: Landlords lack complete deposit coverage for the initial 3-6 months
Payment Default Risk: Tenants may fail to complete installments, leaving partial deposits
Administrative Burden: Tracking payment schedules and enforcing collections
What Are the Risks for Landlords if Tenants Refuse to Pay Security Deposits?
Significant Financial and Operational Exposures
When tenants refuse to pay security deposits and landlords proceed without deposits or with inadequate alternatives, they face substantial risks including uncovered property damage costs averaging $500-$3,000 that must be absorbed entirely by landlords, unpaid rent losses of $1,750/month during tenant defaults without deposit offsets, costly legal collection processes requiring $3,500-$10,000 in attorney fees and court costs often exceeding actual damages, eviction proceedings necessitating 3-5 months and substantial legal expenses, difficulty recovering damages from judgment-proof tenants lacking assets, and reduced financial deterrents for irresponsible tenant behavior when no personal funds are at stake.
Risk Category 1: Property Damage Without Financial Coverage
Uncovered Damage Costs:
Without security deposits, landlords bear 100% of property damage expenses including carpet replacement costing $800-$2,000 per unit, wall repairs from holes, scratches, or unauthorized paint averaging $500-$1,500, appliance damage or replacement costing $300-$1,000 per item, flooring repairs beyond normal wear averaging $600-$1,800, and excessive cleaning costs of $200-$600—collectively averaging $500-$3,000 per incident that deposits would otherwise cover.
Risk Category 2: Unpaid Rent and Eviction Expenses
Financial Losses:
Tenants defaulting on rent create $1,750/month average losses during non-payment periods, while eviction proceedings cost $3,500-$10,000 including attorney fees ($1,500-$5,000), court filing fees ($200-$500), sheriff service costs ($150-$300), and lost rent during 3-5 month eviction processes—totaling $8,750-$18,750 combined losses that deposits would partially offset.
Risk Category 3: Legal Collection Challenges
Recovery Difficulties:
Pursuing tenants for damages or unpaid rent through small claims courts costs $100-$500 in filing fees plus $2,000-$5,000 in attorney fees (if representation is needed), requires 3-12 months for judgments, and often proves uncollectible when tenants lack assets, employment, or bank accounts—making legal collection processes expensive, time-consuming, and frequently fruitless exercises recovering less than 30% of actual losses.
Concrete Example: Deposit Absence Consequences
A landlord rents a $1,500/month property without requiring a security deposit. The tenant stops paying rent after 6 months, causing $2,100 in property damage (carpet, walls, appliances) and accumulating $4,500 in unpaid rent (3 months) before eviction. The landlord incurs:
Property Damage: $2,100 (unrecoverable)
Unpaid Rent: $4,500 (partially collectible at best)
Eviction Costs: $4,000 (attorney fees, court costs)
Turnover Expenses: $3,872 (cleaning, repairs, re-leasing)
Total Loss: $14,472 with zero deposit offset—versus $11,472 net loss if $3,000 deposit had been collected
How Can Landlords Protect Themselves When Tenants Refuse Security Deposits?
Proactive Risk Mitigation Strategies
Landlords protect themselves when tenants refuse security deposits by implementing comprehensive tenant screening through SmartScreen evaluating credit scores (requiring minimum 620-650), rental histories detecting eviction records predicting 3x higher default risk, income verification confirming 2.5-3x monthly rent capacity, employment stability, and landlord references detecting issues in 60-80% of cases; incorporating strong security deposit clauses in lease agreements specifying deposit amounts, due dates, holding procedures, refund timelines, and allowable deductions; offering alternative arrangements including surety bonds, deposit insurance, guarantors, or payment plans when traditional deposits create barriers; and seeking legal counsel ensuring compliance with state deposit caps, holding requirements, refund timelines, and enforcement procedures while protecting landlord rights.
Protection Strategy 1: Comprehensive Tenant Screening
Why Screening Is Critical:
Research demonstrates that comprehensive tenant screening via SmartScreen prevents 90% of profit losses by identifying high-risk applicants early, detecting financial red flags, eviction histories, insufficient income, poor credit, and negative rental references before lease signing—preventing $3,872 in average turnover costs and $3,500-$10,000 in eviction expenses.
Essential Screening Components:
Credit Reports: Verify credit scores averaging 650 for renters, with landlords requiring 620-650 minimums, payment histories, debt-to-income ratios, and collections from previous landlords
Eviction Records: Identify court filings predicting 3x higher future default risk
Income Verification: Confirm 2.5-3x monthly rent capacity, ensuring affordability
Employment Verification: Assess income stability and job continuity
Rental History Verification: Contact previous landlords, detecting issues in 60-80% of cases through payment patterns, property care, and lease compliance confirmation
When tenants refuse deposits, enhanced screening becomes absolutely essential to identify financial instability, payment unreliability, or other risk factors that justify application denial—protecting landlords from applicants unable or unwilling to meet financial obligations.
Protection Strategy 2: Strong Lease Security Deposit Clauses
Critical Lease Provisions:
Incorporate comprehensive security deposit clauses specifying:
Deposit Amount: Clear statement of required deposit (e.g., $2,000 or 2 months’ rent)
Due Date: Specific deadline for deposit payment (e.g., “5 business days before move-in”)
Payment Methods: Acceptable forms (certified check, money order, bank transfer)
Holding Procedures: Escrow account or surety bond compliance per state law
Refund Timeline: State-compliant return deadline (21-30 days typically)
Allowable Deductions: Specific purposes (damages beyond normal wear, unpaid rent, cleaning)
Non-Payment Consequences: Explicit statement that deposit refusal constitutes a lease breach, justifying application denial or eviction
Well-drafted clauses establish the legal foundation for enforcing deposit requirements and set clear contractual obligations that tenants must accept to enter rental agreements.
Protection Strategy 3: Offering Alternatives When Appropriate
While maintaining deposit requirements for most applicants, landlords may selectively offer alternatives to highly qualified candidates facing temporary cash flow issues:
Surety Bonds: For tenants with strong credit (680+) but limited liquid assets
Guarantors: For young professionals with stable employment but limited savings (recent graduates, relocated workers)
Payment Plans: For applicants demonstrating financial responsibility through perfect credit and rental histories
Higher Rent: For tenants preferring ongoing smaller costs over lump sums
However, alternatives should be offered sparingly and only after thorough screening confirms low risk, avoiding financial exposure to high-risk applicants.
Protection Strategy 4: Legal Consultation and Compliance
Professional Legal Guidance:
Consult real estate attorneys or property management legal experts, ensuring:
State Law Compliance: Adherence to deposit caps, holding requirements, and refund timelines
Fair Housing Compliance: Consistent application of deposit requirements across all applicants
Lease Agreement Review: Legally enforceable deposit clauses and provisions
Eviction Procedures: Proper legal processes for deposit non-payment
Collection Strategies: Cost-effective approaches to damage and rent recovery
Legal expertise prevents costly compliance violations while maximizing landlord protection and recovery options.
Frequently Asked Questions
What should I do if my tenant refuses to pay the deposit upfront?
If your tenant refuses to pay the deposit upfront, immediately review your lease agreement confirming deposit requirements are clearly stated, document the refusal in writing via email or certified letter for legal record, explain the legitimate purposes of deposits (property damage coverage, unpaid rent protection, lease compliance incentive), issue a written deposit payment demand specifying 3-5 business day compliance deadline, send demand via certified mail with return receipt for legal proof of notification, explore alternatives if appropriate including surety bonds costing 17.5-35% monthly rent ($262-$525 for $1,500/month rentals), guarantors providing payment assurance, or deposit payment plans over 3-6 months, and legally deny the rental application if the tenant remains non-compliant since landlords have full legal authority to require deposits as standard lease conditions—then utilize SmartScreen’s comprehensive tenant screening for replacement applicants evaluating credit scores, eviction records predicting 3x risk, income verification confirming 2.5-3x rent capacity, and rental references preventing $3,872 turnover costs and 90% profit losses.
Is it legal for tenants to refuse to pay security deposits upfront?
Yes, it is legal for tenants to refuse security deposit payments as they are not criminally obligated to pay, but landlords have full legal authority to deny rental applications from tenants unwilling to pay required deposits since deposits represent standard, lawful lease conditions across all 50 states—meaning tenant refusal to pay deposits does not violate laws but rather results in application denial by landlords exercising legitimate business practices protecting property investments, with Fair Housing compliance requiring only that identical deposit requirements be applied uniformly across all applicants regardless of protected class status, making deposit refusal grounds for rejection without discrimination when landlords consistently enforce deposit policies for all potential tenants preventing selective application based on race, color, national origin, religion, sex, familial status, or disability.
Can landlords refuse to rent to tenants who won’t pay deposits upfront?
Yes, landlords can legally refuse to rent to tenants who won’t pay security deposits upfront since deposit requirements constitute material lease terms that applicants must accept to enter rental agreements, with landlords having no legal obligation to waive or eliminate deposits for unwilling applicants—meaning landlords exercise legitimate business discretion when denying applications from deposit-refusing tenants, similar to rejecting applicants who won’t pay rent, exceed occupancy limits, or violate pet policies, provided deposit requirements are applied consistently across all applicants ensuring Fair Housing Act compliance by avoiding selective enforcement based on protected class status, with 90%+ of landlords requiring deposits as standard practice making deposit refusal severely limit tenant rental options and force extensive property searches for deposit-free rentals typically representing less than 10% of market inventory and often charging premium rents compensating for increased risk.
What are my options if tenants still won’t pay deposits after moving in?
If tenants moved in but still won’t pay agreed-upon security deposits, immediately issue written 3-5 business day pay-or-quit notices specifying deposit amount due and compliance deadline, send notices via certified mail with return receipt establishing legal proof of notification, document all communication attempts and refusals building eviction case files, file unlawful detainer (eviction) actions in local housing courts when tenants fail to comply with notices since deposit non-payment after lease signing constitutes material lease breach justifying eviction, pursue small claims court judgments for unpaid deposits plus court costs and attorney fees when state law allows, report unpaid deposits to credit bureaus damaging tenant credit scores and future rental prospects, and strengthen future prevention through SmartScreen’s comprehensive tenant screening evaluating credit scores, eviction histories predicting 3x risk, income verification, and rental references detecting issues in 60-80% of cases before lease signing—though proceeding to eviction costs $3,500-$10,000 in legal fees and requires 3-5 months, making prevention through thorough screening far more cost-effective than enforcement.
What happens if tenants damage property but haven’t paid deposits upfront?
If tenants damage property but haven’t paid security deposits upfront, landlords bear 100% of repair costs averaging $500-$3,000 including carpet replacement ($800-$2,000), wall repairs ($500-$1,500), appliance damage ($300-$1,000), and excessive cleaning ($200-$600) with zero deposit offset, requiring landlords to pursue small claims court judgments for damage recovery costing $100-$500 in filing fees plus $2,000-$5,000 in attorney fees and requiring 3-12 months for collection, with recovery rates typically below 30% when tenants lack assets, employment, or bank accounts making judgment enforcement difficult—demonstrating why security deposits upfront are essential financial protections preventing $3,872 average turnover costs and 90% profit losses, with SmartScreen’s comprehensive tenant screening identifying high-risk applicants through credit reports showing collections from previous landlords, rental references detecting property damage patterns in 60-80% of cases, and eviction records predicting 3x higher default risk enabling landlords to deny risky applicants before incurring unrecoverable losses.
What should landlords do to prevent tenants from refusing deposits upfront?
Landlords prevent tenant deposit refusal by clearly stating deposit amounts, payment deadlines, and refund terms in rental applications, property listings, and lease agreements eliminating ambiguity, implementing comprehensive tenant screening via SmartScreen evaluating credit scores (minimum 620-650), eviction records predicting 3x risk, income verification confirming 2.5-3x rent capacity, employment stability, and rental references detecting issues in 60-80% of cases to identify financially stable applicants, requesting rental history references from previous landlords confirming deposit payment patterns and financial reliability, requiring completed rental applications including employment and income documentation before property showings ensuring serious applicants, educating applicants about legitimate deposit purposes (property damage protection, unpaid rent coverage, lease compliance incentive) addressing concerns, offering state-compliant alternatives when appropriate including surety bonds ($175-$350 fees), deposit insurance ($29-$50/month), qualified guarantors, or payment plans for creditworthy applicants facing temporary cash constraints, and enforcing consistent deposit policies across all applicants ensuring Fair Housing compliance while protecting investments from $3,872 turnover costs and 90% profit losses.
What are surety bonds, and how much do they cost compared to traditional deposits?
Surety bonds are deposit alternatives where tenants pay non-refundable fees ranging 17.5-35% of one month’s rent to third-party companies (Rhino, TheGuarantors, Jetty, SureDeposit) that guarantee landlords up to full traditional deposit amounts (typically 1-2 months’ rent) for property damage or unpaid rent claims—for example, $1,500/month rentals requiring $3,000 traditional deposits (2 months) alternatively accept surety bonds costing $262-$525 annual fees (17.5-35% of $1,500), representing 91% upfront cost reduction enabling immediate move-in for tenants lacking liquid assets, though surety fees are non-refundable annual expenses versus refundable traditional deposits, with 3-year tenancy paying $787-$1,575 total surety fees compared to $3,000 one-time refundable deposit (returned at lease end), making surety bonds more expensive long-term but reducing move-in barriers while providing landlords identical $3,000 coverage for damages and unpaid rent, though tenants remain 100% financially liable as surety companies pursue reimbursement for all claims similar to traditional deposit deductions.
Are there states with new security deposit laws in 2026?
Yes, several states implemented new security deposit laws effective 2025-2026 including California AB 12 (effective July 2024) capping deposits at 1 month’s rent maximum (reduced from previous 2-3 months), California AB 2801 requiring pre-move-in and post-move-out photographs documenting property condition, California AB 414 (effective January 2026) allowing electronic deposit refunds to tenant-designated bank accounts and requiring single checks payable to all adult co-tenants unless written agreements specify otherwise, Georgia HB 404 (effective January 2025) capping deposits at 2 months’ rent maximum and requiring landlords to hold deposits in escrow accounts or post surety bonds with 30-day refund deadlines and 3x damages penalties for willful wrongful withholding, New York continuing rent-stabilized unit deposit restrictions, and Florida maintaining no statutory caps though typical 1-2 months practices—making landlords consult state-specific regulations ensuring compliance with evolving deposit caps, holding requirements, refund timelines, electronic payment rules, and penalty provisions.
TL;DR: Tenant Won’t Pay Deposit Upfront Essentials
Legal landlord right: Deny applications for deposit refusal (legal across all states)
Immediate actions: Written demand, 3-5 day deadline, certified notice
Surety bond alternative: $175-$350 fees vs. $2,000-$3,000 deposits
Deposit insurance: $29-$50/month ($348-$600 annually)
State deposit caps: California 1 month, Georgia 2 months
Eviction consequence: 3x default risk from deposit refusal patterns
Property damage risk: $500-$3,000 unrecovered costs without deposits
Screening importance: 90% profit loss prevention via SmartScreen
Turnover cost: $3,872, average prevented by deposits
Legal costs: $3,500-$10,000 eviction expenses
Conclusion:
When tenants won’t pay security deposits upfront, landlords possess full legal authority to deny rental applications since security deposits represent standard, lawful lease requirements protecting against property damage averaging $500-$3,000, unpaid rent losses of $1,750/month, and turnover costs totaling $3,872 per incident—with immediate landlord actions including reviewing lease agreements confirming deposit clauses, documenting refusal in writing via certified mail, issuing written deposit payment demands with 3-5 business day compliance deadlines, and legally rejecting non-compliant applicants when deposit requirements are applied consistently across all potential tenants ensuring Fair Housing Act compliance, while exploring alternatives including surety bonds costing 17.5-35% of monthly rent ($175-$350 for $1,000/month rentals or $262-$525 for $1,500/month properties) as non-refundable annual fees guaranteeing landlords up to full traditional deposit amounts, deposit insurance programs charging $29-$50 monthly ($348-$600 annually) providing $5,000 standard coverage, guarantor or co-signer arrangements requiring financially qualified third parties assuming payment liabilities, deposit payment plans spreading costs over 3-6 months reducing upfront barriers while eventually providing full coverage, or higher monthly rent increases of $50-$150 (3-10% premiums) compensating for deposit elimination though creating $600-$1,800 annual and $1,800-$5,400 three-year costs exceeding traditional refundable deposits—yet proceeding without adequate deposits exposes landlords to 100% uncovered property damage costs, $1,750/month rent default losses without offsets, $3,500-$10,000 eviction expenses requiring 3-5 months and substantial legal fees, $3,872 average turnover costs fully borne by property owners, and difficulty recovering losses through small claims courts costing $100-$500 filing fees plus $2,000-$5,000 attorney fees with recovery rates typically below 30% when judgment-proof tenants lack attachable assets—making comprehensive tenant screening through SmartScreen absolutely essential for identifying financial red flags including credit scores below 620 indicating payment unreliability, eviction records predicting 3x higher future default risk, insufficient income failing 2.5-3x monthly rent requirements, negative rental references from previous landlords, collections from prior properties, chronic late payment patterns, and unstable employment preventing 90% of profit losses through early detection of high-risk applicants before lease signing, while landlords must ensure legal compliance with evolving state security deposit regulations including California’s 1 month rent maximum cap effective July 2024 (reduced from previous 2-3 months), electronic refund provisions and co-tenant check requirements under AB 414 effective January 2026, Georgia’s 2 months rent maximum cap under HB 404 effective January 2025 with 30-day refund deadlines and 3x damages penalties for willful wrongful withholding, escrow account or surety bond holding requirements, 21-30 day refund timelines across most jurisdictions, itemized deduction statement mandates, pre-move-in and post-move-out photo documentation requirements, and Fair Housing Act consistent application standards avoiding selective enforcement based on protected class status—with strong lease security deposit clauses specifying amounts, due dates, payment methods, holding procedures, refund timelines, allowable deductions, and non-payment consequences establishing clear contractual obligations and legal enforcement foundations, legal consultation ensuring compliance and maximizing recovery options, documented screening criteria applied uniformly preventing discrimination claims while protecting investments, and recognition that while deposit alternatives reduce tenant barriers facilitating occupancy, traditional refundable deposits remain the gold standard providing maximum landlord protection, strongest tenant accountability incentives, and lowest long-term tenant costs compared to non-refundable surety fees and monthly insurance premiums—ultimately transforming security deposit management from potential conflict points into strategic risk mitigation tools protecting rental property investments, ensuring financial sustainability, and maintaining high-quality tenant selection standards throughout 2026 and beyond.
Professional Resources: