

Why Is Tenant Screening Important?
Tenant screening (including credit checks) is the cornerstone of risk management for landlords and property managers. By reviewing credit history, employment, and rental references, you reduce the likelihood of:
Missed rent payments or defaults
Property damage
Stressful evictions or legal disputes
For example, a thorough credit check can show whether a tenant pays bills on time, helping you predict their likelihood of prompt rent payments.
What Is a Credit Score—and Why Does It Matter?
A credit score summarizes a tenant’s financial reliability and responsibility, factoring in:
Payment History (do they pay bills on time?)
Credit Utilization (how much credit is in use?)
Credit Age (how long have accounts been open?)
Credit Mix (do they responsibly use various credit types?)
Recent Inquiries (any recent credit applications?)
Higher scores typically mean less risk for you as a landlord. However, focusing exclusively on the score can sometimes overlook otherwise qualified tenants, such as those recovering from a single past setback or building credit for the first time.
Can You Refuse to Rent to Someone Based on Credit Score?
Yes, landlords can lawfully deny rental applications due to low credit scores, as long as their decisions are consistent, transparent, and adhere to fair housing laws.
Understanding Fair Housing Laws
The HUD Fair Housing Act protects applicants from discrimination based on race, color, religion, sex, national origin, disability, or family status. To comply:
Apply your minimum credit score criteria to every applicant, without exception.
Avoid using different standards for similar applicants.
Never use credit scores as a pretext for unlawful discrimination.
Example:
If you set a minimum credit score of 650, you must use that same threshold for all prospective tenant, no matter their background or personal details.
How Credit Scores Factor Into Smart, Legal Decisions
Financial Responsibility:
A strong credit score correlates with on-time rent payments and respect for lease agreements.
Risk Management:
Lower scores may signal frequent late payments, high debt, or prior financial instability—all potential problems for landlords.
Negotiating Terms:
Applicants with lower credit can sometimes offset risk with a higher deposit, a guarantor, or documentation of stable income or excellent references.
Using SmartScreen for Better Tenant Selection
SmartScreen gives landlords a full picture—not just a single number—by integrating:
Credit reports from sources like TransUnion
Rental and criminal background checks
Customizable screening packages for your properties
Case Example:
Suppose an applicant has a 620 credit score but steady employment and glowing landlord references. Instead of outright denial, a landlord opts for a higher deposit or a co-signer, ensuring risk is balanced with fairness.
SmartScreen helps you make informed, fair decisions while reducing legal risk.
Real-World Scenarios
Automatic Denial: Applicant’s score is well below your published standard, and other applicants qualify—denial is justified and compliant.
Conditional Acceptance: Score is low, but reliable income and good references prompt a conditional offer (larger deposit, co-signer, shorter lease).
Appeal/Dispute: Applicant disputes an error on their credit report. Using SmartScreen and open communication, you let the applicant provide proof, keeping your process fair.
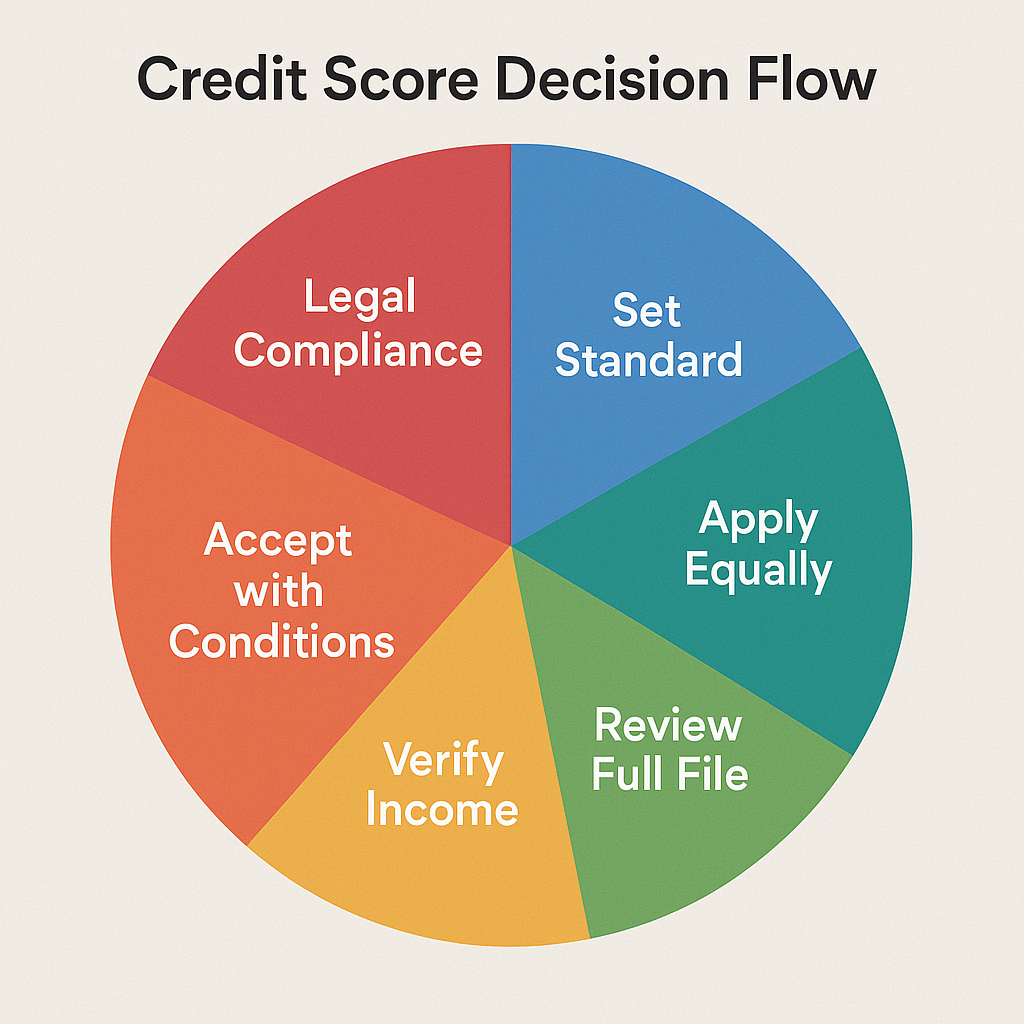
Credit Score Decision Flow for Landlords
Frequently Asked Questions / TL;DR
Can I refuse to rent to someone with a low credit score?
Yes, as long as you apply your standard consistently, explain adverse decisions, and do not discriminate.
What should I consider besides credit score?
Always look at the full picture—income stability, rental references, and criminal history—to make the most informed choice.
Can tenants dispute their credit scores?
Yes. The Fair Credit Reporting Act gives tenants the right to dispute errors; always consider the documentation or evidence they provide.
How does SmartScreen help me avoid legal risk?
SmartScreen ensures every report is FCRA and Fair Housing compliant, applies your standards consistently, and protects sensitive applicant data.
What if a tenant’s credit score is low but their income is stable?
Consider additional documentation, a higher deposit, or a co-signer—balancing risk management with opportunity for a reliable renter.
Author Credentials
This article was produced in consultation with SmartScreen, an industry-trusted expert in tenant background checks and compliance, and reviewed for accuracy using standards from HUD.gov, Nolo, NARPM.org, and MySmartMove.com.
Bottom Line:
Using credit scores for tenant selection is legal and effective—if you stay fair, document your standards, and review the whole applicant file. SmartScreen gives you the tools and reports you need to comply and choose the best tenants, every time.